Market overview and structural scope of the Factor XIa Inhibitors Market
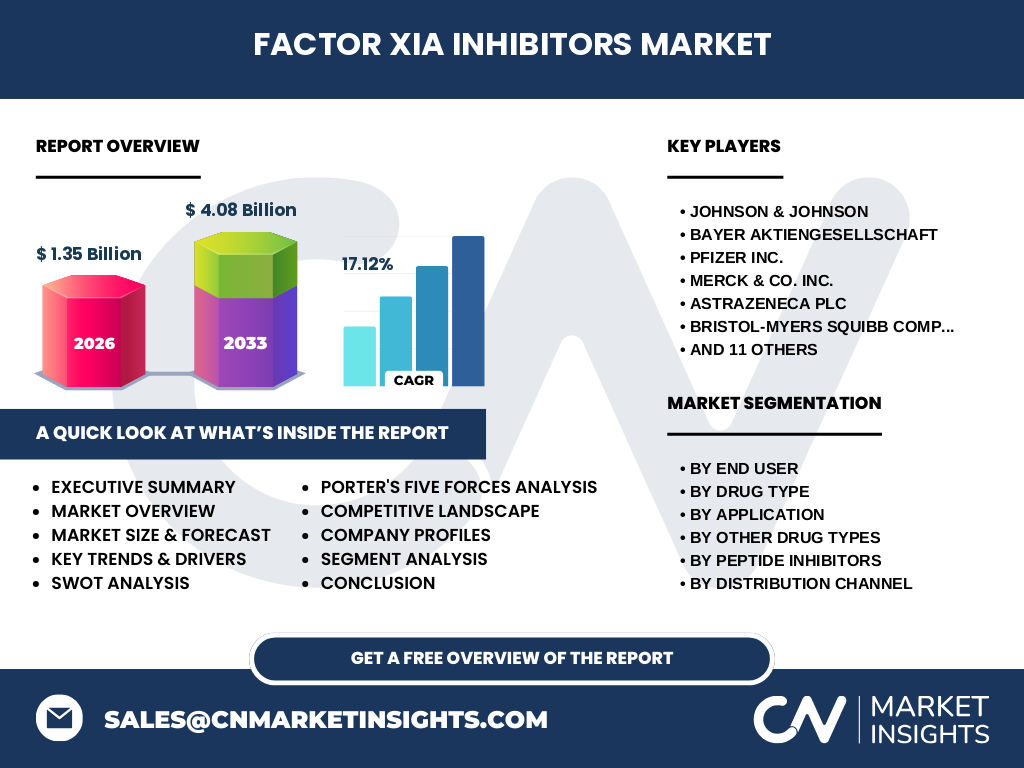
Our analysis indicates that the Factor XIa Inhibitors Market represents a transformative frontier in anticoagulation therapeutics, engineered to prevent thrombosis without compromising hemostasis. Valued at 1.35 Billion in 2026, the industry encompasses advanced pharmaceutical agents targeting intrinsic coagulation pathways, mitigating bleeding risks associated with traditional therapies like direct oral anticoagulants.
What core catalysts and barriers shape the Factor XIa Inhibitors Market industry trends?
The market is propelled by a rising global geriatric demographic and an escalating prevalence of cardiovascular disorders requiring safer antithrombotic solutions. However, stringent regulatory scrutiny by agencies like the FDA and complex clinical trial requirements for synthetic peptide inhibitors act as notable market restraints.
Emerging Innovation Waves and Clinical Adoption Patterns
The sector is witnessing a decisive pivot toward precision medicine, particularly through ribonucleic acid based therapies and antisense oligonucleotide platforms pioneered by innovators like Ionis Pharmaceuticals Inc. These modalities offer sustained target knockdown, shifting the paradigm from daily oral dosing to infrequent, long-acting parenteral administration.
How did pandemic disruptions redefine the Factor XIa Inhibitors Market analysis trajectory?
The COVID-19 pandemic caused severe clinical trial recruitment delays and supply chain bottlenecks for raw biochemical precursors. Nevertheless, heightened awareness of thrombosis risks in viral pathologies ultimately accelerated institutional investments, positioning the market for robust post-pandemic recovery and accelerated pipeline maturation.
Competitive Benchmarking and Industry Concentration
Industry concentration is characterized by aggressive licensing agreements between biopharmaceutical titans and agile innovators. Major players like Bayer Aktiengesellschaft and Bristol-Myers Squibb Company dominate late-stage clinical pipelines, while specialized firms such as Anthos Therapeutics drive niche advancements in target specific antibody therapies.
Executive Summary: Navigating the 17.12% CAGR Growth Horizon
Our comprehensive evaluation confirms that the Factor XIa Inhibitors Market is poised for explosive expansion, scaling from 1.35 Billion in 2026 to 4.08 Billion by 2033 at a remarkable CAGR of 17.12%. Strategic asset acquisitions and expanding clinical indications remain critical for capturing high-yield market segments.
Market Forecast Projections Through 2033
Driven by commercialization milestones of phase III clinical assets, the market trajectory indicates exponential revenue acceleration post-2027. Reaching the projected 4.08 Billion valuation by 2033 requires successful label expansions into deep vein thrombosis and stroke prevention indications across global healthcare systems.
Detailed Segmentation Analysis Across Therapeutics and Delivery
Segmentation spans multiple dimensions: By End User covers Hospitals, Clinics, and Research Institutes. By Drug Type includes Small Molecule Inhibitors, Monoclonal Antibodies, and Peptide Inhibitors. By Route Of Administration differentiates between Oral and Injectable formulations, catering to diverse acute and chronic care requirements.
Geographic Distribution and Regional Performance Dynamics
Geographic performance reflects healthcare expenditure disparities and clinical trial density. North America currently leads adoption due to robust clinical trial infrastructure, while the Asia-Pacific region demonstrates the fastest growth trajectory, propelled by expanding hospital networks in urban centers across China and Japan.
In-Depth Regional Review of Clinical Adoption Hotspots
North America maintains dominance backed by early regulatory clearances and high-density adoption within specialized cardiovascular research institutes. Meanwhile, European markets exhibit steady uptake constrained by localized health technology assessments, whereas emerging economies focus on expanding retail and hospital pharmacy access.
Strategic Positioning of Leading Industry Participants
Industry leaders leverage distinct competitive advantages: Johnson & Johnson and Pfizer Inc. utilize massive global commercial footprints to fast-track late-stage assets, whereas specialized entities like Sirius Therapeutics Inc. and Cadrenal Therapeutics Inc. focus on disruptive RNA and orphan drug applications.
Porter's Five Forces Assessment of Competitive Pressures
Rivalry is intense among established pharmaceutical conglomerates vying for first-mover advantage in stroke prevention. Bargaining power of buyers remains moderate due to high switching costs in chronic care, while threat of substitutes is low given the unique uncoupling of thrombosis and hemostasis unique to Factor XIa inhibition.
SWOT Analysis of the Global Therapeutics Landscape
Key strengths include superior safety profiles over traditional anticoagulants, while weaknesses involve high research and development capital expenditure. Opportunities lie in expanding into cancer-associated thrombosis, against threats of stringent generic small molecule competition and prolonged reimbursement negotiations.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with specialized chemical synthesis of raw peptide components and recombinant protein expression. This flows through contract manufacturing organizations into finished dosage forms, distributed via hospital pharmacies and specialized clinics to end-users managing chronic thromboembolic disorders.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize portfolios featuring oral direct small molecule inhibitors and long duration injectable antibodies. Collaborations with agile developers like CRISPR Therapeutics and Ono Pharmaceutical Co. Ltd. offer prime avenues for high-alpha returns in this rapidly evolving therapeutic sector.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Factor XIa Inhibitors Market represents a definitive paradigm shift in cardiovascular pharmacology. Achieving commercial success requires balancing aggressive clinical pipeline investments with strategic navigation of reimbursement hurdles and regional regulatory frameworks across major global territories.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are derived through rigorous data triangulation, synthesizing primary stakeholder interviews with key opinion leaders, secondary trade registry analytics, and macroeconomic healthcare expenditure indicators to ensure absolute accuracy in market sizing and growth projections.
Scope of the Report and Analytical Parameters
This report evaluates the global market across specified drug types, routes of administration, and distribution channels from 2026 to 2033. Limitations include inherent uncertainties surrounding future regulatory approvals and unforeseen macroeconomic shifts affecting global healthcare procurement budgets.
Recent Developments, Strategic Partnerships, and Pipeline Milestones
Recent industry momentum is underscored by landmark licensing deals and positive phase II clinical readouts. Companies like AstraZeneca plc, Novartis, and Merck & Co. Inc. have actively consolidated pipeline assets through strategic acquisitions, aiming to capture dominant shares of the burgeoning antithrombotic market.